Can I Sell My House Before My Mortgage Term Ends in Alberta?
Seller Tips
Can I Sell My House Before My Mortgage Term Ends in Alberta?
The Direct Answer
Yes. You can sell your home at any time, and your mortgage is paid out from the sale proceeds on closing. What you may owe is a prepayment penalty for paying off the mortgage before the term ends. The Financial Consumer Agency of Canada says a penalty can apply if you pay off the full mortgage early, including when you sell, and that it "can cost thousands of dollars." Whether you pay one, and how much, depends on your lender, your rate type and how much of the term is left. You can often reduce or avoid it by porting your mortgage to your next home or by waiting until the term ends.
How the Penalty Is Calculated
For most closed mortgages in Canada, the penalty is one of two amounts.
- Three months' interest: This is the minimum penalty. It is an amount equal to three months of interest on what you still owe. Variable-rate mortgages commonly use this method, although lenders can calculate the interest differently, so check your contract.
- Interest rate differential (IRD): On fixed-rate mortgages, the penalty is usually the higher of three months' interest or the IRD. The IRD compares the interest remaining on your current term at your rate against the rate your lender could charge today. If your rate is above current rates and you have a long time left on the term, the IRD can be much larger. The FCAC gives an example of a $200,000 balance at 6% with 36 months left, where the IRD is $12,000 compared with $3,000 for three months' interest.
Lenders calculate the IRD differently. Some large banks base it on posted rates, while monoline lenders often use your actual contract rate, so the same mortgage can cost very different amounts to break at different lenders. Your mortgage contract sets out the formula.
Ways to Reduce or Avoid the Penalty
- Port your mortgage: If you are buying another home, ask your lender whether you can keep your existing rate, terms and conditions. The FCAC notes this avoids breaking your contract and starting a new one. Porting usually has conditions, such as buying within a set period and qualifying for the new amount, so ask early.
- Use your prepayment privileges: Most mortgages allow a set amount of extra payments each year without penalty. The FCAC notes unused amounts usually do not carry over. Prepaying before you break the contract lowers the balance the penalty is calculated on.
- Time the sale to your term: If your renewal date is close, setting your closing date at or after the term end can remove the penalty. Ask your lender how far ahead of renewal you can close.
- Check a longer term: Under section 10 of the federal Interest Act, on a mortgage with a term of more than five years, the borrower can prepay after five years by paying three months' further interest. Most Canadian terms are five years or less, so this rarely applies, but check yours.
What to Do Before You List
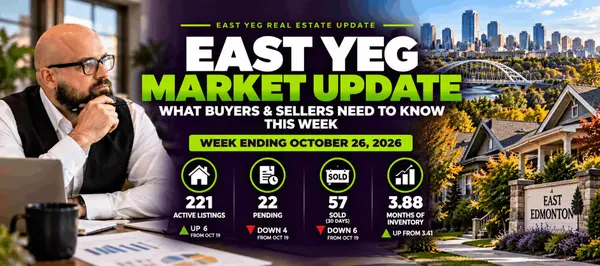
Call your lender or broker and ask for a written estimate of the payout and penalty if you were to close on a specific date, and ask whether your mortgage is portable. Do this before listing, because the penalty is a real cost of selling and should be part of your net proceeds calculation. In Alberta your lawyer will arrange the payout and discharge of your mortgage at closing, so give them the lender's statement as early as you can. With homes in East YEG (East Edmonton) taking time to sell and 40.3% of active listings reduced as of October 26, 2026, it also helps to know your real bottom line before you set a price. Our weekly East YEG market update shows where the market stands.
BT Group East YEG Market Research is prepared by Jason Beattie, REALTOR® with eXp Realty, using current REALTORS® Association of Edmonton MLS® market activity across the East YEG neighbourhoods tracked in this report. Short-term neighbourhood statistics can fluctuate when relatively few properties sell; individual property values should not be inferred from neighbourhood averages alone.
This is general information, not mortgage or legal advice. Your lender's written payout figure and your lawyer are the final word on your own situation.
Thinking About Selling in East YEG?
What Would It Take to Get Top Dollar for Your Home?
Between negotiation trends, price reductions, and how fast homes are actually moving right now, the numbers above only tell part of the story. I'll give you a straight answer on what your specific home is worth today, and what it would take to maximize your sale price in this market.
Get Your Free Home Valuation Book a Free Strategy CallFrequently Asked Questions
Can I sell my house before my mortgage term ends?
Yes. Your mortgage is paid out from the sale proceeds at closing. A prepayment penalty may apply, and the Financial Consumer Agency of Canada notes that paying off the full mortgage early, including when you sell, can trigger one.
How much is the penalty to break a mortgage in Canada?
It is usually the higher of three months' interest or the interest rate differential. In the FCAC's example of a $200,000 balance at 6% with 36 months left, the differential is $12,000 compared with $3,000 for three months' interest. Your lender's contract and written payout statement set your actual figure.
Can I avoid the penalty by porting my mortgage?
Often, if you are buying another home. Porting lets you keep your existing rate and terms instead of breaking the contract, but lenders set conditions such as timing and qualifying for the new amount, so ask your lender before you list.
Jason Beattie
REALTOR® | eXp Realty | BT Group
780-791-9633 | Jason.Beattie@eXpRealty.com
Book a Free Strategy CallCategories
- All Blogs (110)
- downsizing (17)
- East YEG (60)
- Eco-friendly Homes (1)
- Edmonton Bylaws (6)
- Events & Community News (43)
- First Time Home Buyer (40)
- Gardening & Landscaping (1)
- Home Buying Tips (55)
- Home Insurance (5)
- Home Selling Tips (45)
- How to (16)
- increase home value (16)
- Interior Design (2)
- Local Market Trends (68)
- market Influences (79)
- Market Update (53)
- Migration (6)
- Mortgage Info (8)
- Moving & Relocation (73)
- Neighborhood Profiles (54)
- Real Estate FAQs (93)
- Real Estate Investment (11)
- Real Estate Laws & Regulations (5)
- Technology in Real Estate (2)
Recent Posts

"With 25+ years in Edmonton real estate, I track weekly sales activity across all 17 East YEG neighbourhoods so buyers and sellers get real numbers, not guesswork. If you're weighing a move in East Edmonton, I'm happy to walk you through what the data means for your street."